You have not yet added any article to your bookmarks!
Join 10k+ people to get notified about new posts, news and tips.
Do not worry we don't spam!
Post by : Saif Rahman
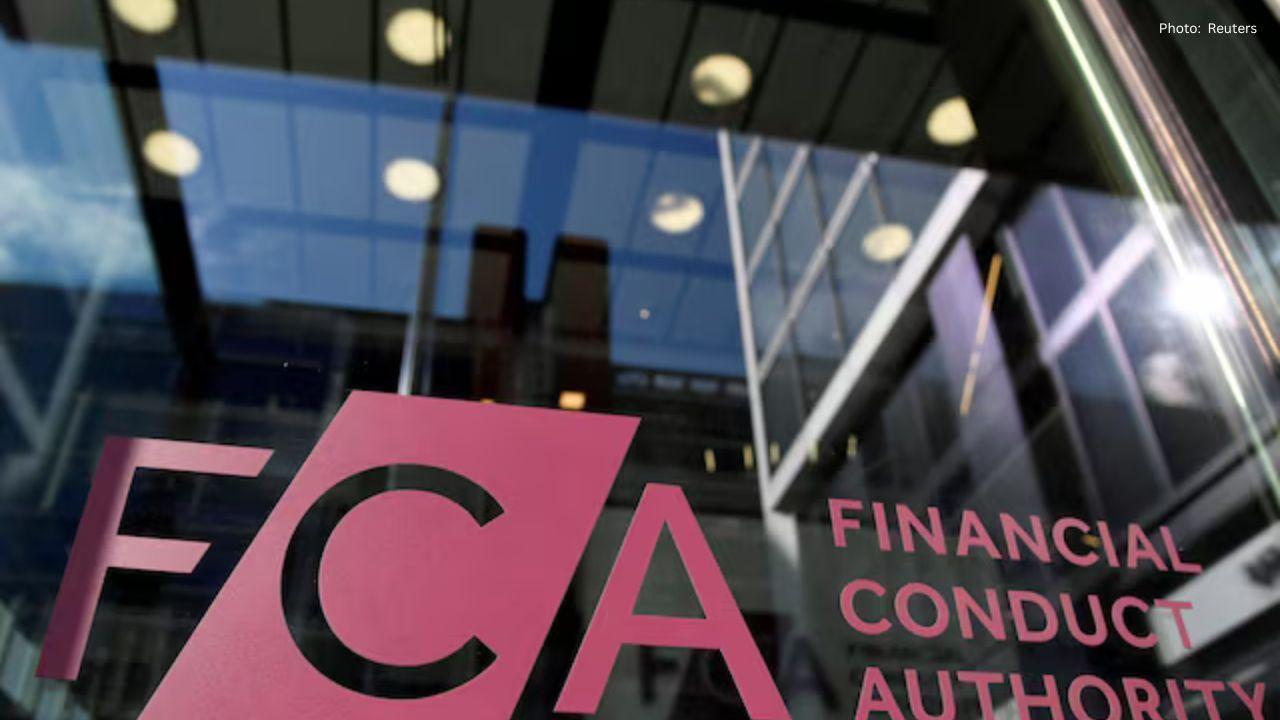
The United Kingdom is set to unveil a more straightforward and flexible framework governing financial advice, aimed at enabling a larger segment of the population to grasp investment concepts and make more informed financial decisions. The Financial Conduct Authority (FCA), the primary regulatory body for finance in the UK, announced that these modifications will come into effect in April.
This new approach, dubbed “targeted support,” will empower financial advisers to offer guidance on investment and retirement savings without the burden of exhaustive personal assessments. This marks a significant departure from existing regulations, which many argue are overly stringent and costly for the average citizen.
Currently, merely 9% of the UK populace seeks regulated financial advisory services, a figure that pales in comparison to other major economies. The FCA posits that convoluted regulations have made financial advice prohibitively expensive and challenging to secure, resulting in widespread uncertainty among individuals regarding savings management and future planning.
The forthcoming adjustments are part of a comprehensive initiative to motivate British households to allocate more funds into shares, bonds, and pension schemes. At present, UK households invest substantially less than their counterparts in the European Union or the United States, with only 19% of financial assets allocated to retail investments from 2020 to 2023. In contrast, EU households invested 38%, while U.S. households invested 56%.
Sarah Pritchard, deputy chief executive at the FCA, articulated the agency's ambition to transform this trend. She emphasized that enhanced investment from everyday citizens could bolster the nation’s economy and ensure greater long-term financial security for families.
Reactions from industry stakeholders have been largely positive. Yvonne Braun, Policy Director for the Association of British Insurers, remarked that the introduction of targeted support may lead to significant improvements. She highlighted the need for straightforward and reliable guidance for individuals grappling with complex financial decisions, particularly concerning retirement planning.
The FCA has made several refinements to the earlier rule drafts based on public feedback. Notably, advisers will no longer be mandated to conduct continuous monitoring after providing targeted support, as this advice is intended as one-time assistance. Additionally, the requirement for advisers to ensure comprehensive customer understanding of service fees has been eliminated.
According to the new regulations, firms providing targeted support will need to identify distinct groups of consumers with shared preferences or objectives. This will enable them to offer relevant, simplified advice tailored to those groups. However, any firm seeking to deliver this new type of service will need to apply for special authorization starting in March.
In parallel, the FCA has initiated a consultation regarding updated regulations for digital pension planning tools. Numerous companies have claimed that existing regulations hinder the development of clear, interactive tools that help individuals visualize their future pensions. The regulator seeks to enhance the functionality and appeal of these tools.
The proposed changes reflect the UK’s commitment to cultivate a stronger investment culture amid rising living costs, pension uncertainties, and eroding confidence in financial markets. By streamlining access to advice and reducing associated costs, the government aims to empower millions of individuals to take charge of their financial destinies.
Whether this new strategy will effectively resonate depends on the financial sector's adaptation and consumer comfort with the revised offerings. Nevertheless, these reforms represent a pivotal move towards making financial advice more accessible and practical for the general populace.

APEC Members Emphasise Safe and Responsible Use of Artificial Intelligence
APEC members discuss responsible AI use, digital innovation and data governance as China and the US

Union of European Clubs Challenge UEFA and EFC Over EU Competition Rules
UEC files an EU competition complaint against UEFA and EFC, challenging club representation, governa

Mohammed Shami Retires From Test Cricket, Eyes White-Ball Career
Mohammed Shami retires from Test cricket after 13 years, with 229 wickets. He will continue playing
Singapore Warns Users About Privacy and Security Risks of AI Agents
Singapore warns users about AI agent security risks, data privacy, online scams and unauthorised acc
Chris Lynn Completes One-Month Ban After Positive Cocaine Test
Australian cricketer Chris Lynn completes a one-month ban after a positive cocaine test during the T
Djokovic Eyes Strong Season Finish as Health Improves Ahead of Paris Masters
Novak Djokovic reports improved health and performance as he targets a strong Paris Masters finish a